
By the Omozing Credit Team, which includes IIT and IIM alumni · Updated October 2026 · 8-minute read
Credit score and credit report: the two things lenders read
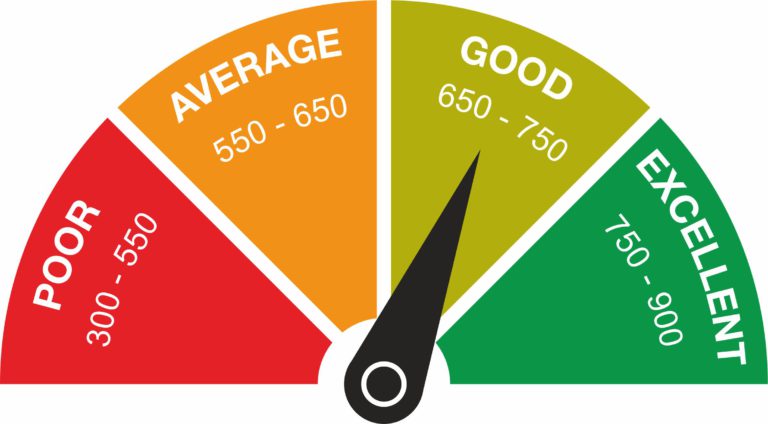
Your credit report is the record: every loan and credit card in your name, how much you owe, whether each EMI was paid on time, and which lenders have checked your file recently. Your credit score is a three-digit summary of that record, on a scale of 300 to 900. India has four credit bureaus: TransUnion CIBIL, Experian, Equifax and CRIF High Mark. Each produces its own score, so your numbers can differ slightly between bureaus.
The score gets you through the door; the report decides the offer. Two people with a 690 can get very different answers if one has a single late payment from three years ago and the other has a settled loan from last year.
What each score band usually means for a personal loan
The 300–900 scale and how lenders typically treat each band
A general guide, not any lender’s published policy. Cut-offs differ by lender, product, salary and employer, and can change at any time.
| Score band | Who usually lends | What to expect |
|---|---|---|
| 750–900 | Banks, NBFCs, fintech lenders | Widest choice, lowest rates, higher amounts, faster approvals. |
| 700–749 | Most NBFCs and many banks | Good approval odds; rate depends on salary, employer and existing EMIs. |
| 650–699 | NBFCs and fintech lenders that read the full report | Approval depends on why the score is lower; expect closer checks and a smaller first loan. |
| 600–649 | Selected NBFCs, often with a co-applicant | Possible for steady salaried borrowers with clean recent history; Omozing considers this band. |
| Below 600 | Very few regulated lenders for unsecured loans | Work on the report first, or consider a secured option. Beware of apps promising loans “without CIBIL”. |
| No score (NH/NA) | Some NBFCs and fintech lenders | New-to-credit borrowers are judged on salary and banking; a small first loan builds history. |
Notice that approval is not the only thing that moves with your score. A lower band usually changes the shape of the offer: a smaller first loan, a shorter tenure, a higher rate or a request for a co-applicant. That is why a borrower at 640 who needs ₹3 lakh may be better served by a ₹1.5 lakh loan repaid flawlessly for a year, followed by a top-up, than by applying to ten lenders for the full amount and collecting rejections and enquiries.
The reason behind a score matters as much as the score itself. A 660 caused by high credit card usage is quick to fix. A 660 caused by a written-off loan needs explanation, proof of closure and time. Know which one you have before you apply.
What lenders check besides the score
Recent repayment
Late payments in the last 12 months weigh far more than an old slip. Lenders look at days past due (DPD) on each account.
Income and FOIR
Your fixed obligations to income ratio: how much of your take-home already goes to EMIs. A common rule of thumb is to keep total EMIs within about half of take-home pay.
Account status
“Settled” or “written off” on any account is a bigger concern than a modest score. Lenders want to know what happened and whether it is resolved.
Recent enquiries
Many loan applications in a few weeks suggest credit hunger. Apply selectively rather than to every app at once.
Employer and job stability
A regular salary credited to a bank account, and some time with the current employer, both help.
Credit mix and usage
A credit card used up to its limit every month reads as stress, even if paid on time. Lower usage helps.
Omozing’s eligibility, in plain numbers
Rates start from 11% a year, with a processing fee of 3% to 7% plus GST. Your exact rate, fees and annual percentage rate (APR) are shown in the Key Fact Statement before you sign. A credit officer reads your full report, so an older problem that has since been fixed is weighed in context. You can also add a co-applicant, such as a spouse, family member or even a friend, to strengthen your application. Full details are on our personal loan page.
How to move up a band before you apply
Pull your own report
You are entitled to one free full credit report from each bureau every calendar year. Checking your own report does not lower your score.
Fix errors
Closed loans still showing as open, accounts that are not yours, or wrong late-payment marks can drag your score down. Raise a dispute with the bureau; our CIBIL dispute guide explains how.
Clear overdue amounts
Bring every account to zero overdue. An account that is current reads very differently from one that is still past due.
Lower card usage
Pay card balances down well below the limit before the statement date, not just on the due date.
Pause new applications
Give it a few months without fresh enquiries, and then apply to one or two lenders that fit your band.
Stay consistent
Every on-time EMI adds to your record. Improvement is gradual and no one can promise a specific score by a specific date.
If you would like structured help, the Omozing Credit Score Booster works through your report with you.
Score between 600 and 750?
Omozing considers salaried applicants from a score of 600, with a credit officer reading the whole report. See what you could qualify for.
Frequently asked questions
What is the minimum CIBIL score for a personal loan?
There is no single minimum. Many banks prefer 750 and above, many NBFCs work with scores from the high 600s, and Omozing considers salaried applicants from 600. The rest of your report and your income matter too.
Can I get a personal loan with a 650 credit score?
Often, yes, from NBFCs and fintech lenders that read the full report. Steady salary, no recent late payments and moderate existing EMIs improve your chances. A co-applicant can help further.
Is a 700 credit score good for a personal loan?
A 700 is a fair score that most NBFCs and many banks will consider. Moving it towards 750 usually unlocks lower rates and higher amounts.
Do different bureaus give different scores?
Yes. CIBIL, Experian, Equifax and CRIF High Mark each calculate their own score from the data reported to them, so small differences are normal.
Does checking my own credit score reduce it?
No. Checking your own score is a soft enquiry and does not affect it. Only lender checks made when you apply for credit are recorded as hard enquiries.
What is Omozing’s eligibility for a personal loan?
Salaried, with a take-home salary of ₹40,000 or more a month and a credit score from 600. You need a six-month salary-account bank statement and your latest salary slip.
I have no credit history. Can I still get a loan?
Some lenders lend to new-to-credit borrowers based on salary and banking. Starting with a small loan or a credit card and repaying on time builds a score over time.
Omozing is the digital lending brand of Aparampaar Finance Private Limited, an RBI-registered non-deposit-taking NBFC. See our regulatory disclosures and grievance redressal process.